Alternative Investment Funds, often abbreviated as AIFs, have become a buzzword among sophisticated investors, especially High Net Worth Individuals (HNIs).
What is an AIF in India?
An Alternative Investment Fund (AIF) is a privately pooled investment vehicle set up in India as a trust, company, limited liability partnership (LLP) or body corporate, which collects money from sophisticated Indian or foreign investors and invests it under a defined investment policy (Regulation 2(1)(b), SEBI (Alternative Investment Funds) Regulations, 2012). Every AIF must register with SEBI as a Category I, II or III fund before it raises money.
These funds focus on non-traditional, less liquid assets such as private equity, venture capital, and real estate. Unlike mutual funds, AIFs are characterized by higher minimum investment requirements, longer lock-in periods, and a focus on specialized investment strategies. AIFs are becoming a favoured choice for discerning investors, including High Net Worth Individuals (HNIs), Institutional Buyers and Family Offices. With their promise of high returns across diverse asset classes, AIFs are attractive for those aiming to diversify and enhance their portfolios. While these funds often involve complex strategies and higher risk, they provide unique opportunities for capital appreciation and exposure to non-traditional asset classes.
Overview of AIFs in India [Updated Data]
As of March 2026, there are 1,849 registered AIFs in India, up from 732 five years ago, reflecting 135% growth in the last five years alone. This domain has witnessed remarkable growth, with total commitments crossing Rs. 15.74 lakh crore (Rs. 15.74 trillion) as of December 2025, with net investments reaching Rs. 6.45 lakh crore in the same period, approximately 127% higher than Rs. 2.84 lakh crore recorded at the end of FY 2021-22. This growth translated to a substantial Rs. 7.07 trillion jump within three years. AIFs have shown superior IRRs (Internal Rate of Returns) compared to traditional Asset Management Companies (AMCs). This higher performance has led to a higher valuation premium for AIFs over traditional AMCs. The accredited investor ecosystem has expanded sharply alongside AIF growth. As of April 2026, the number of accredited investors stood at 2,773, up from just 649 a year earlier, a rise of over 300% in twelve months. Accredited investors held AIF units with a par value of approximately Rs. 1.91 lakh crore as of December 2025, accounting for roughly 30% of total AIF investments.
The latest SEBI data shows the industry has kept growing. As of 30/09/2026, total commitments raised by AIFs stood at ₹18.68 lakh crore, up 24.1% year on year, with funds raised of ₹7.99 lakh crore and investments made of ₹7.50 lakh crore. Category II funds account for ₹13.91 lakh crore of those commitments, Category III for ₹3.61 lakh crore and Category I for ₹1.17 lakh crore (SEBI, Data relating to activities of AIFs, quarter ended 30/09/2026). For the full year to 31/03/2026, commitments grew 25.6% to ₹16.94 lakh crore and cumulative net investments reached ₹6.76 lakh crore (SEBI Annual Report 2025-26). Accredited investors numbered 3,820 as of 31/07/2026, close to six times the 649 recorded a year earlier, against a total AIF investor base of about 96,000 (SEBI consultation paper on the accredited investor framework, 13/08/2026).
The total assets under management (AUM) of AIFs have grown at a CAGR (Compound Annual Growth Rate) of 28% between June FY19 and June FY24. 75% of AIFs have successfully generated positive alpha, compared to a lower alpha generation in equity AMCs, where 51% of large-cap funds and 26% of mid-cap funds were unable to deliver alpha over the past year.
Equity AIFs have outperformed the BSE Sensex TRI index PME+ for five consecutive years. 80% of registered AIFs fall under Category I & II (venture capital, private equity, debt funds). ~₹4.4Tn invested, with ~70% allocated to unlisted securities. 44% of new schemes (2022-2024) were launched by first-time fund managers, highlighting strong market confidence.
The alternatives market in India had a total AUM of approximately USD 136 billion as of December 2024, growing at over 13% CAGR and projected to reach USD 247 billion by 2029. Private credit AUM within this stands at approximately USD 25 billion. AIFs are projected to represent 15% of the total AUM in India’s wealth management industry by 2027.
In light of the burgeoning AIF industry, its regulatory authority, the Securities and Exchange Board of India (SEBI), hasn’t remained a silent observer. SEBI has proactively been fortifying protocols to guarantee investor safety, heighten transparency, and ensure fair practices within the AIF guidelines.
So, the question arises, what exactly are AIFs? And how do they function within the Indian regulatory landscape?
What are Alternative Investment Funds (AIFs)?
Meaning and Definition
An Alternative Investment Fund (AIF) is a privately pooled and managed investment vehicle established in India structured as a trust, company, Limited Liability Partnership (LLP), or body corporate that gathers funds from sophisticated Indian or foreign investors for investment according to a defined investment policy for their benefit.
Some key terms used in AIFs
- Carry: Carry or carried interest in AIF is akin to performance fees which is paid to the investment manager as a share of the AIF’s profits which the investment manager is entitled to if they exceed a specific threshold return. Carry is typically in the range of 15-20% of the profits earned by the AIF in excess of the specified threshold.
- Hurdle / Preferred rate of return: Minimum percentage of returns that an investor earns before the Investment Manager can catch-up and charge carry to investor.
- Catch-up: Catch-up allows the investment manager to earn the hurdle rate of return on its investment in the AIF but only after the investors have received their investment along with the hurdle rate of return on such investment.
- Distribution waterfall: Provides for an order of specified priority in which the distributions are made by AIF which includes the capital contributions, fees, hurdle, catch up (if any), carry, etc.
- Closing: Closing is the date fixed by the Investment Manager as a cut-off date to obtain capital commitment from investors.
Important Characteristics of AIFs
To better understand how AIFs differ from traditional investments, consider these core features:
- Lower Liquidity: AIFs often have lower liquidity compared to traditional securities, which can make it challenging to access or sell investments quickly.
- Higher Risk Profile: These funds are specifically designed for investors seeking higher returns, though this potential comes with increased risk.
- Unique Fee Structures: While AIFs generally have higher management fees and minimum investment requirements than traditional mutual funds or ETFs, they often benefit from lower transaction costs.
- Complex Valuation: Due to the unique nature of alternative assets and less standardized reporting, valuing these investments can be a complex process.
- Diverse Asset Classes: AIFs provide broad diversification by investing in various assets, including private equity, real estate, commodities, and infrastructure.
- Distinct Risk-Return Profiles: These funds exhibit different risk and return characteristics than traditional stocks or bonds, offering the potential for enhanced returns alongside elevated risk.
- Regulatory Framework: Every AIF operates within a specific regulatory framework, and its legal structure may vary depending on local regulations and jurisdiction.
Regulatory Framework for AIF in India
AIFs in India are governed by four layers of law. The SEBI (Alternative Investment Funds) Regulations, 2012 set the core rules and were last amended by the Third Amendment Regulations, 2026, notified on 09/10/2026. The SEBI Master Circular for AIFs dated 03/06/2026 (HO/19/34/11(6)2025-AFD-POD1/I/12928/2026) consolidates the operating rules. The Foreign Exchange Management Act, 1999 (FEMA) governs foreign investment, and the Income-tax Act, 2025 governs tax from 01/04/2026.
In India, AIFs operate under the purview of the Securities and Exchange Board of India (SEBI).
Since their establishment in the late 1980s, Venture Capital Funds (VCFs) have been a significant focus for the government to bolster the growth of specific sectors and early-stage companies. However, the desired outcomes in supporting emerging sectors and startups were not realized, largely due to regulatory uncertainties. Recognizing this challenge, in 2012, the Securities and Exchange Board of India unveiled the SEBI (Alternative Investment Funds) Regulations. This was done to categorize AIFs as a unique asset class, similar to Private Equities (PEs) and VCFs.
Any entity wishing to function as an AIF must seek registration with SEBI. While there are various legal structures under which an AIF can be established, such as a trust, a company, an LLP, or a body corporate, trusts are the most commonly chosen form in India.
A typical AIF structure looks like the following:
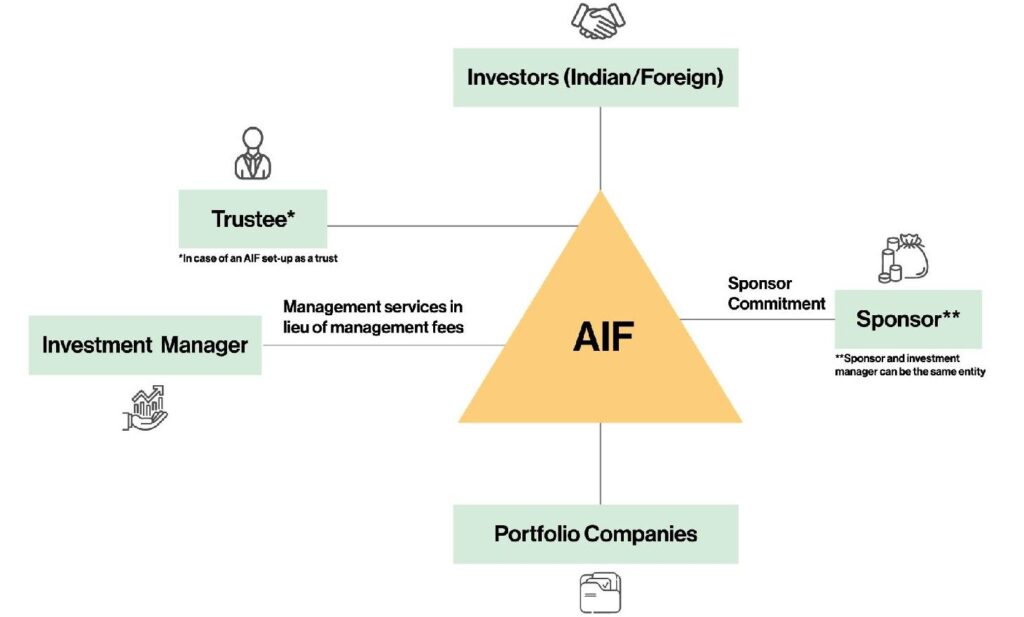
The entities are:
- Settlor: Person who settles the trust with a nominal initial settlement
- Trustee: Person in charge of the overall administration and management of the Trust. In practice, this responsibility is then outsourced to the investment manager.
- Contributor: Investor to the Trust (AIF) and makes a capital commitment to the AIF
- Sponsor: Face of the AIF i.e. Person who sets up the AIF
- Investment Manager: Brain of the AIF i.e. Person who is appointed to manage the investments
- Custodian: Safeguards the securities and assets of the AIF and facilitates settlement of transactions.
- Merchant Banker: Assists with due diligence certification for PPM.
- Registrar and Transfer Agent (RTA): Maintains investor records, processes capital calls and distributions, and handles investor communications and reporting.
It’s noteworthy that the roles of the Sponsor and Investment Manager can be unified, with one entity performing both functions.
SEBI GARUDA Mechanism (May 2026 Update)
In May 2026, SEBI released a consultation paper proposing the GARUDA (Green-Channel: AIF Rollout Upon Document Acknowledgement) mechanism to streamline scheme launches. Under the proposed framework, regular AIF schemes would be permitted to launch within 10 working days of filing the PPM with SEBI through a merchant banker, compared to the then applicable 30-day waiting period. For Accredited Investor-only schemes and Angel Funds, SEBI has proposed eliminating the merchant banker requirement entirely. These schemes would be allowed to launch immediately upon filing, with an undertaking from the AIF manager’s CEO and Compliance Officer replacing the merchant banker due-diligence certificate. SEBI will continue post-launch scrutiny on a sample, risk-based basis. Public comments on the proposal were open until 01 June 2026.
The proposal has since been adopted. SEBI’s Board approved GARUDA on 19/06/2026, the SEBI (Alternative Investment Funds) (Second Amendment) Regulations, 2026 took effect on 14/07/2026, and SEBI circular HO/19/19/11(2)2026-AFD-RAC2/I/17617/2026 dated 30/07/2026 set out the operating rules by substituting paragraph 2.4 of the Master Circular. A regular scheme can now launch 10 working days after the PPM is filed with SEBI through a SEBI-registered merchant banker that is not an associate of the AIF, its sponsor, manager or trustee, unless SEBI advises otherwise. Filing the PPM does not amount to SEBI approval.
Table: Scheme launch timelines under GARUDA (from 14/07/2026)
| Scheme type | PPM filed through a merchant banker? | When the scheme can launch | SEBI comments to be incorporated? |
|---|---|---|---|
| Regular scheme | Yes, an independent merchant banker | 10 working days after filing, unless SEBI advises otherwise | Yes (Regulation 12(3A)) |
| Accredited Investors only fund | No; undertaking by the manager’s CEO and Compliance Officer | On filing; a first scheme from the date of registration | No |
| Large value fund (LVF) | No; undertaking by the manager’s CEO and Compliance Officer | On filing; a first scheme from the date of registration | No |
| Angel Fund | No | PPM can be circulated from the date of registration | No |
For a new AIF, the first scheme still cannot launch before SEBI grants the certificate of registration, so the registration timeline, not the 10-day window, usually sets the launch date.
What are the key provisions of the SEBI AIF regulations?
The SEBI (Alternative Investment Funds) Regulations, 2012 set the entry, investment and exit rules for every AIF. Definitions sit in Regulation 2, registration and categories in Regulations 3 to 7, fund-raising and investor limits in Regulation 10, scheme launch in Regulation 12, investment conditions in Regulations 15 to 18, Angel Funds in Regulations 19A to 19G, general obligations in Regulation 20 and winding up in Regulation 29.
Table 4: Key provisions of the SEBI (AIF) Regulations, 2012, as amended up to 15/10/2026
| Regulation | Subject | Current rule | Latest change |
|---|---|---|---|
| 2(1)(b) | Definition of AIF | Privately pooled vehicle in India (trust, company, LLP or body corporate) that collects funds from Indian or foreign investors and invests under a defined investment policy | Unchanged since 2012 |
| 2(1)(ab) | Accredited investor | Accreditation by an accreditation agency or a specified SEBI-regulated entity, on income, net worth or securities market exposure | Third Amendment Regulations, 2026 (09/10/2026) |
| 3 | Registration and categories | Registration is mandatory, as Category I, II or III; change of category needs SEBI approval | Unchanged |
| 10 | Investment in an AIF | ₹20 crore minimum corpus per scheme; ₹1 crore minimum per investor (₹25 lakh for employees or directors of the AIF or manager); maximum 1,000 investors per scheme | Accredited investors exempt from the ₹1 crore minimum; ₹1,000 minimum for individuals in social impact funds from 18/04/2026 |
| 12 | Launch of schemes | PPM filed with SEBI through a merchant banker; launch 10 working days after filing; no scheme fee on the first scheme | Second Amendment Regulations, 2026 (14/07/2026) |
| 13 | Tenure | Category I and II schemes close-ended, minimum 3 years, extendable by up to 2 years with approval of two-thirds of unit holders by value | Unchanged |
| 15 | General investment conditions | Up to 25% of investable funds in one investee company for Category I and II, 10% for Category III; LVFs 50% and 20% | LVF relaxation |
| 16 to 18 | Category-wise conditions | Category I and II: borrowing only for temporary needs; Category III: total exposure up to 2 times NAV | Master Circular, 03/06/2026 |
| 19A to 19G | Angel Funds | Accredited investors only; ₹10 lakh to ₹25 crore per investee company | Second Amendment Regulations, 2025 (08/09/2025) |
| 20 | General obligations | Custodian for every AIF; compliance officer; units in dematerialised form | Custodian mandate extended to all AIFs by circular dated 12/01/2024 |
| 25 | Dispute resolution | Investor disputes go to mediation, conciliation or arbitration; manager losses cannot be charged to the fund | Third Amendment Regulations, 2026 |
| 29 | Winding up | One-year liquidation period; in-specie distribution; inoperative fund status | Amendment Regulations, 2026 (18/04/2026) |
The definition in Regulation 2(1)(b) excludes family trusts set up for relatives, ESOP trusts, employee welfare and gratuity trusts, holding companies, securitisation and reconstruction company funds, and any pool of funds directly regulated by another regulator in India, such as mutual funds and collective investment schemes.
SEBI AIF regulations: amendments in 2025 and 2026
The AIF rulebook changed nine times between September 2025 and October 2026. The biggest shifts were accredited-investor-only Angel Funds, the AI-only fund category, faster scheme launches under GARUDA and wider accreditation routes. The table lists each change against the rule it replaced.
Table 5: Amendment tracker for the SEBI AIF framework, 2025 to 2026
| Date | Instrument | What changed | Earlier position |
|---|---|---|---|
| 08/09/2025 | SEBI (AIF) (Second Amendment) Regulations, 2025; circular SEBI/HO/AFD/AFD-POD-1/P/CIR/2025/128 (10/09/2025) | Angel Funds raise only from accredited investors; ₹10 lakh to ₹25 crore per investee; 200-investor cap removed; co-investment schemes for accredited investors | Self-declared angel investors; ₹25 lakh to ₹10 crore; 200 investors per scheme |
| 18/11/2025 | SEBI (AIF) (Third Amendment) Regulations, 2025; circular dated 08/12/2025 | AI-only fund category; LVF minimum cut; conversion route for existing schemes | LVF minimum of ₹70 crore |
| 18/04/2026 | SEBI (AIF) (Amendment) Regulations, 2026 (notified 16/04/2026) | ₹1,000 minimum for individuals in social impact funds; inoperative fund status under Regulation 29(10A) | ₹2 lakh minimum |
| 30/04/2026 | SEBI fast-track circular | Launch 30 days after PPM filing unless SEBI advises otherwise | Launch after SEBI comments |
| 03/06/2026 | SEBI Master Circular for AIFs | Consolidates circulars issued up to 31/05/2026 | Master Circular dated 07/05/2024 |
| 16/06/2026 | Circular HO/19/34/11(2)2026-AFD-POD1/I/13764/2026 | Retention of proceeds beyond fund life; inoperative fund process | No framework |
| 14/07/2026 and 30/07/2026 | SEBI (AIF) (Second Amendment) Regulations, 2026; GARUDA circular | 10 working days for regular schemes; AI-only funds, LVFs and Angel Funds launch on filing; no fee on the first scheme | 30 days; fee on every scheme |
| 07/09/2026 | Circular HO/19/34/11(7)2025-AFD-POD1/I/20626/2026 | Legacy Angel Funds get until 31/03/2027 to move to accredited investors only | 08/09/2026 |
| 15/10/2026 | SEBI (AIF) (Third Amendment) Regulations, 2026 (SEBI/LAD-NRO/GN/2026/326, 09/10/2026) | Accreditation through securities market exposure; persons resident outside India deemed accredited; new Regulation 25 | Income and net worth tests only |
Categories of AIFs in India: Types of AIF
Under the SEBI AIF Regulations, AIFs are classified into 3 distinct categories namely Category 1, Category 2 and Category 3 AIFs. Each category serves a unique purpose and is characterized by specific investment conditions and varying degrees of regulatory oversight. Below is an overview of the categories, highlighting their primary purpose and key conditions:
| Parameters | Category I AIF | Category II AIF | Category III AIF |
| Definitions | Funds with strategies to invest in start-up or early stage ventures or social ventures or SMEs or infrastructure or other sectors or areas which the government or regulators consider as socially or economically desirable. Includes: Venture Capital Funds (angel funds are a sub-category of VCFs)SME fundsSocial Impact FundsInfrastructure FundsSpecial Situation Funds | Funds that cannot be categorized as Category I AIFs or Category III AIFs. These funds do not undertake leverage or borrowing other than to meet day-to-day operational requirements and as permitted in the AIF Regulations. Examples: Private Equity or Debt Funds | Funds which employ diverse or complex trading strategies and may employ leverage including through investment in listed or unlisted derivatives. Examples: Hedge funds or funds which trade with a view to make short-term returns |
| AIF Minimum ticket size | INR 1 crore | INR 1 crore | INR 1 crore |
| AIF Minimum fund size | INR 20 crore | INR 20 crore | INR 20 crore |
| Open or close ended AIF | Close-ended fund | Close-ended fund | Can be open or close-ended fund |
| Tenure | Minimum tenure of 3 years | Minimum tenure of 3 years | NA |
| Continuing interest of Sponsor / Manager (a.k.a skin in the game) | Lower of:2.5 % of corpusINR 5 crores | Lower of:2.5 % of corpusINR 5 crores | Lower of:5 % of corpusINR 10 crore |
| Investment outside India | Permissible subject to SEBI approval | Permissible subject to SEBI approval | Permissible subject to SEBI approval |
| Concentration norms | Cant invest more than 25% in 1 investee company | Cant invest more than 25% in 1 investee company | Cant invest more than 10% in 1 investee company |
| Borrowing | To not borrow funds except for : (a) temporary funds not more than 30 days (b) less than 4 occasions in a year Borrowing shall be limited to the lower of:i) 10% of investable fundsii) 20% of the proposed investment in the investee companyiii) undrawn commitment from investors other than the defaulting investors | (Same as Category 1 AIF) | Can engage in leverage & borrowing as per prescribed rules |
| Overall restrictions / compliances | Low | Medium | High |
| SEBI registration fees | INR 500,000 | INR 1,000,000 | INR 1,500,000 |
| Per scheme filing fees | INR 100,000 | INR 100,000 | INR 100,000 |
Table 1: Categories of AIFs
Apart from the categories mentioned above, any of the three categories of AIFs can be classified as a large-value fund (LVFs), provided that each investor is an “accredited investor” as per the AIF Regulations and invests a minimum of INR 25 crores in the AIF. LVFs have certain investment and compliance related exemptions.
Three Table 1 parameters need reading with later changes. Every AIF scheme must now appoint a custodian, whatever its corpus (SEBI circular dated 12/01/2024, read with Regulation 20(11)). The registration fees of ₹5,00,000, ₹10,00,000 and ₹15,00,000 remain as set in Part A of the Second Schedule, with a separate ₹1,00,000 application fee, but no scheme fee is payable on the first scheme an AIF launches (proviso to Regulation 12(1), from 14/07/2026). For LVFs, the concentration limit is 50% of investable funds for Category I and II and 20% for Category III, and Category III total exposure is capped at 2 times NAV. Category I and II AIFs must keep a 30-day cooling-off period between two periods of permitted borrowing.
Category I AIFs: Nurturing Growth and Social Impact
Category 1 Alternative Investment Funds (AIFs) are investment vehicles designed to promote economic development, entrepreneurship, innovation, and social impact. These funds channel capital into sectors that are considered socially or economically desirable by regulators and the government, and therefore often receive policy support, incentives, or concessions.
Regulated by Securities and Exchange Board of India (SEBI), Category I AIFs primarily focus on long-term value creation rather than short-term liquidity.
Investment Focus of Category I AIFs
Category I AIFs invest in areas that contribute directly to nation-building and economic expansion, including:
- Startups and early-stage ventures
- Venture capital and angel-backed businesses
- Social ventures with measurable impact
- Small and Medium Enterprises (SMEs)
- Infrastructure projects
- Special situation and stressed asset opportunities
These investments are typically unlisted, early-stage, or financially complex, which increases both risk and return potential.
Fund Structure & Tenure of Category I AIFs
- Fund Type: Strictly close-ended
- Unit Listing: Optional, permitted only after final fund closure
- Minimum Tenure:
- 3 years
- Extendable by up to 2 additional years with approval of two-thirds of investors (by value)
This structure aligns investor capital with long-term developmental outcomes.
Leverage, Borrowing & Risk Profile of Category I AIFs
- Leverage for Investments: Not permitted
- Temporary Borrowing:
- Allowed only for operational needs
- Limited to 10% of the investable corpus
- Maximum duration: 30 days
Key Risk Characteristics:
- High growth potential
- Low liquidity
- Elevated risk due to early-stage, distressed, or impact-oriented investments
Taxation of Category I AIFs
Category I AIFs enjoy pass-through tax status:
- Income (excluding business income) is taxed directly in the hands of investors
- Taxation applies as per the investor’s applicable income tax slab
- The fund itself does not bear tax at the entity level for pass-through income
Sponsor Commitment Requirements
To ensure alignment of interest between fund managers and investors:
- Minimum Sponsor Contribution:
- 2.5% of the fund corpus or ₹5 crore (whichever is lower)
- Angel Funds:
- 2.5% of corpus or ₹50 lakh (whichever is lower)
- Under the revised angel fund framework of 10/09/2025, the manager’s or sponsor’s continuing interest is maintained in each investment of the Angel Fund, as set out in Table 2.
Custodianship Requirement
- Mandatory custodian appointment only if:
- Fund corpus exceeds ₹500 crore
- Below this threshold, custodianship remains optional
Since SEBI’s circular dated 12/01/2024, this threshold no longer applies: every Category I AIF scheme must appoint a SEBI-registered custodian, and schemes already holding an investment on that date had until 31/01/2025 to comply (Regulation 20(11), SEBI (AIF) Regulations, 2012).
Sub-Categories of Category I AIFs
1. Venture Capital Funds (VCFs)
Venture Capital Funds invest in early-stage and high-growth unlisted companies with scalable business models. These funds play a vital role in:
- Promoting innovation and entrepreneurship
- Supporting companies until IPO, acquisition, or strategic exit
- Generating long-term capital appreciation
VCFs carry higher risk, but also the potential for outsized returns.
2. Angel Funds
Angel Funds are a specialized sub-category of Venture Capital Funds focused on seed-stage and early-stage startups.
Key Characteristics:
- Capital pooled from individual or institutional angel investors
- Minimum investment per investor: ₹25 lakh
- From 08/09/2025, no minimum applies per investor, because Angel Funds can raise money only from accredited investors (SEBI (AIF) (Second Amendment) Regulations, 2025).
- Provide not only funding but also:
- Mentorship
- Industry expertise
- Strategic networking
Angel Funds act as the first institutional capital for many startups. Angel Funds also hold a distinct categorization under the AIF Regulations. These funds are a sub-category of Category I AIFs: VCFs, primarily designed to acknowledge and support the unique role of angel investors in the startup ecosystem. The key characteristics of Angel funds are summarised below:
| Parameters | Category 1 AIFs |
| Conditions | Minimum corpus: None Minimum number of investors: 5 Accredited Investors to declare first closeMaximum investors per scheme: No limit |
| Continuing interest of Sponsor / Manager(a.k.a skin in the game) | Minimum continuing interest to be maintained in each investment of the Angel Fund at higher of:0.5% of investment amount or INR 50,000 |
| Angel Investor | An Accredited Investor or KMP of an angel fund / manager |
| Accredited Investor (AIs) | “accredited investor” means any person who is granted a certificate of accreditation by an accreditation agency and who:Individuals, HUFs, Family trusts and sole proprietorship meeting any of the following criteria:Annual income >= INR 2 crore; or Net-worth >= INR 7.5 crore (with >= INR 3.75 crore in financial assets); orAnnual income >= INR 1 crore and net-worth >= INR 5 crore (with >= INR 2.5 crore in financial assets)Partnership firms: Eligible only if each partner meets the above criteriaTrusts (excluding family trusts) and Body-corporates: Net-worth >= INR 50 crores |
| Investments | Can invest directly in startups (without launching separate schemes)Minimum investment: Rs. 10 lakhs Maximum investment: Rs. 25 croresLock-in: 1 year (Reduced to 6 months if its a third party sale)Can invest 25% of the Fund corpus outside India subject to SEBI approvalCan invest entirely into one startup (with minimum 2 Accredited Investors) |
| Open or close ended fund | Close-ended |
| Investor Approval | Manager to obtain prior approval from each angel investor before making investment |
| SEBI registration fees | INR 200,000 |
Table 2: Angel Funds
The accredited investor definition in Table 2 widened from 15/10/2026. An individual, HUF, family trust or sole proprietorship can also qualify through securities market exposure of at least ₹5 crore; an LLP, another body corporate or a non-family trust qualifies with net worth of at least ₹50 crore or securities market exposure of at least ₹20 crore; and persons resident outside India, as defined under FEMA, 1999, are deemed accredited (Regulation 2(1)(ab), as amended by SEBI/LAD-NRO/GN/2026/326 dated 09/10/2026). A specified SEBI-registered or regulated entity can now grant accreditation, alongside an accreditation agency.
Angel Funds registered on or before 10/09/2025 have until 31/03/2027 to move to accredited investors only. Until then they cannot offer an investment to more than 200 non-accredited investors, and after that date they cannot accept contributions from non-accredited investors for any investee company (SEBI circular HO/19/34/11(7)2025-AFD-POD1/I/20626/2026 dated 07/09/2026). Existing investors keep the investments already made.
3. Special Situation Funds (SSFs)
Special Situation Funds invest in financially distressed assets, including:
- Stressed loans acquired under Reserve Bank of India (RBI) Master Directions
- Security Receipts issued by RBI-registered Asset Reconstruction Companies (ARCs)
- Companies undergoing insolvency under the Insolvency and Bankruptcy Code (IBC)
Additional Conditions:
- 6-month lock-in on acquired security receipts
- Investments often linked to resolution plans or restructuring outcomes
These funds aim to unlock value from distressed but viable businesses.
4. Social Venture Funds
Social Venture Funds pursue a dual mandate:
- Financial returns
- Measurable social or environmental impact
They invest in organizations addressing challenges such as:
- Education
- Healthcare
- Sustainable development
- Livelihood generation
- Environmental conservation
These funds demonstrate that profitability and social good can coexist.
Category II: Private Equity & Debt Funds (Residual)
Category 2 Alternative Investment Funds (AIFs) represent the most widely used AIF category and include all funds that do not fall under Category I or Category III. These funds are designed to provide investors with structured exposure to private markets while operating under defined regulatory constraints. Category II AIFs are funds that neither qualify for incentives under Category I nor engage in leverage or complex trading strategies like Category III. They are not permitted to use leverage for investment purposes, except for temporary borrowing strictly to meet day-to-day operational requirements. These funds typically invest in unlisted entities, real estate, or distressed assets and are structured as close-ended vehicles with a defined tenure.
Investment Focus of Category II AIFs
Category II AIFs primarily invest in:
- Private Equity (PE)
- Debt Instruments of Unlisted Companies
- Real Estate Assets
- Distressed or Stressed Assets
This investment approach offers diversification through unlisted private markets and is generally associated with moderate-to-high risk and stable long-term return potential.
Fund Structure and Tenure of Category II AIFs
- Structure: Strictly close-ended
- Minimum Tenure: 3 years
- Extension: Up to 2 additional years with approval
- Listing: Optional
The close-ended nature aligns with the long-term investment horizon required for private market value creation.
Leverage and Borrowing:
- Investment Leverage: Prohibited
- Permitted Borrowing: Allowed only for temporary operational requirements
This restriction ensures lower systemic risk and preserves the long-term investment focus of the fund.
Taxation of Category II AIFs
- Tax Status: Pass-through
- Capital Gains Taxation (at investor level):
- Long-Term Capital Gains (LTCG): 12.5%
- Short-Term Capital Gains (STCG): 20%
The pass-through mechanism ensures that income is taxed directly in the hands of investors rather than at the fund level.
The 12.5% and 20% rates above apply to listed equity shares on which securities transaction tax is paid. Long-term gains on unlisted shares and most other capital assets are also taxed at 12.5% without indexation from 23/07/2024, but short-term gains on them are taxed at the investor’s slab or applicable rate, and interest and dividends are taxed as ordinary income. From 01/04/2026, these rates sit in Sections 196, 197 and 198 of the Income-tax Act, 2025, which replace Sections 111A, 112 and 112A of the 1961 Act.
Sponsor Commitment
- Minimum Contribution: 2.5% of the total fund corpus or ₹5 Crore, whichever is lower
This requirement ensures sponsor alignment with investor interests.
Custodianship
- Mandatory: Only if the fund corpus exceeds ₹500 Crore
Custodianship provides an additional layer of asset safety and oversight for large funds.
The ₹500 crore threshold was removed by SEBI’s circular dated 12/01/2024, so every Category II scheme now needs a custodian regardless of size.
Key Sub-Types of Category II AIFs
1. Private Equity Funds (PEFs)
Private Equity Funds form a major component of Category II AIFs. These funds invest in mature, unlisted companies with the objective of growth, expansion, acquisitions, or restructuring. Investments are typically made by acquiring controlling or significant minority stakes. Fund managers actively engage with portfolio company management to enhance operational efficiency and value creation.
- Typical Lock-in Period: 4 to 7 years
- Investment Horizon: Long-term, reflecting private company growth cycles
2. Debt Funds
Debt Funds under Category II focus on investing in debt instruments issued by unlisted companies. These may include structured debt, mezzanine financing, or convertible debt. Such funds provide alternative financing solutions for companies that may not rely solely on traditional bank funding.
- Use of Capital: Expansion, working capital, or project-specific needs
- Return Profile: Interest income and potential capital appreciation
3. Fund of Funds (FoFs)
Fund of Funds under the AIF framework invest in other AIFs instead of directly investing in companies or assets. This structure enables diversification across multiple strategies and fund managers through a single investment.
- Key Advantage: Broader exposure to alternative investment strategies
- Investor Benefit: Reduced individual due diligence effort
Category III AIFs: Complex Strategies and Short-Term Returns
Category 3 AIFs are designed to capitalize on short-term and medium-term market opportunities through active trading strategies. Unlike Category I and II AIFs, these funds are permitted to use leverage and sophisticated financial instruments. Their goal is not merely to outperform a benchmark but to achieve positive returns in both rising and falling markets.
Investment Focus of Category III AIFs
Category III AIFs primarily invest in:
- Hedge Funds
- PIPE Funds (Private Investment in Public Equity)
- Derivative-based trading strategies
These funds actively trade across asset classes and market segments to exploit inefficiencies and price movements.
Trading Strategies and Risk Profile of Category III AIFs
Category III AIFs employ diverse and complex trading strategies, including but not limited to:
- Long-short equity
- Market-neutral strategies
- Arbitrage strategies
- Global macro strategies
- Event-driven strategies
They frequently use leverage (borrowed capital to amplify returns) and derivatives such as futures, options, and swaps for both hedging and speculative purposes. Due to these characteristics, Category III AIFs exhibit high volatility and complex valuation methodologies, making them suitable only for sophisticated investors with higher risk tolerance.
Fund Structure and Tenure of Category III AIFs
- Structure: Flexible: Open-ended or Close-ended
- Minimum Tenure: No fixed minimum tenure for open-ended schemes
This flexibility allows fund managers to dynamically adjust portfolios based on market conditions.
Leverage and Borrowing
- Leverage: Permitted
- Purpose: Active trading and hedging
- Conditions: Subject to regulatory limits and mandatory disclosures
- Total gross exposure, long and short after permitted offsets, cannot exceed 2 times the NAV of the fund, and the fund reports its exposure to the custodian daily (SEBI Master Circular for AIFs, chapter on Category III exposure).
The ability to employ leverage differentiates Category III AIFs from other AIF categories.
Taxation of Category III AIFs
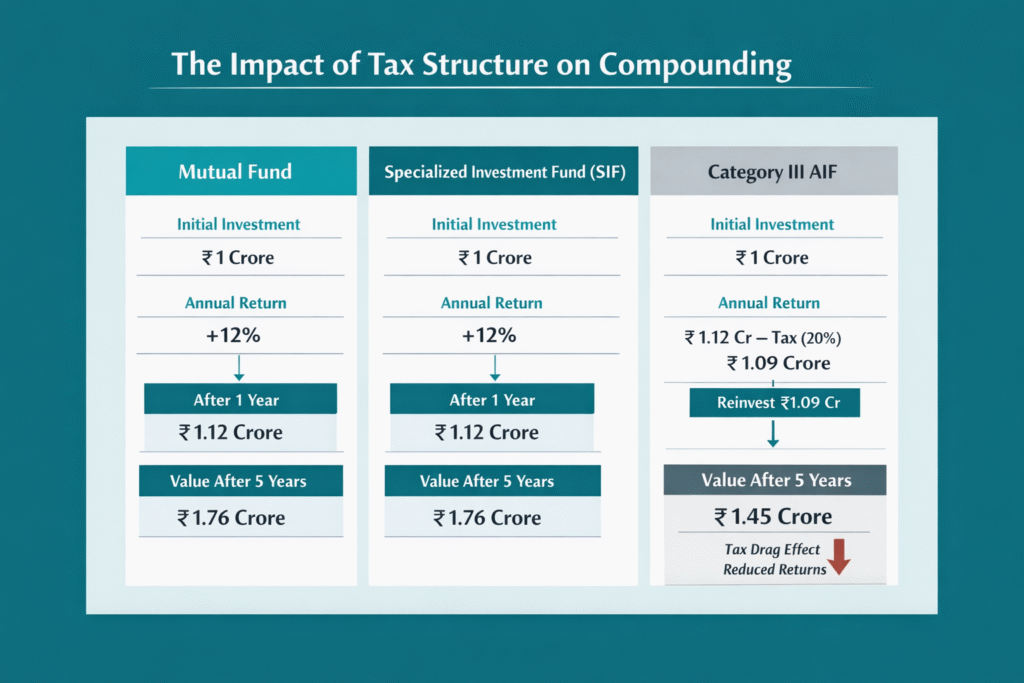
- Tax Treatment: Fund-level taxation (No pass-through status)
- Tax Rate: Maximum Marginal Rate (approximately 42.7%)
- The 42.7% figure reflects the old tax regime with the 37% surcharge. Where the new regime applies, surcharge is capped at 25% and the maximum marginal rate works out to 39%, the rate used later in this article.
- Impact: Tax is paid by the fund before distributions are made to investors
Sponsor Commitment
- Minimum Requirement: 5% of the total corpus or ₹10 Crore, whichever is lower
This higher sponsor contribution reflects the elevated risk and complexity of Category III AIFs.
Custodianship
- Requirement: Mandatory for all Category III AIFs
- Applicability: Irrespective of the fund corpus size
Custodianship ensures enhanced transparency, asset safety, and regulatory oversight.
Hedge Funds within Category III AIFs
Hedge Funds are the most prominent segment of Category III AIFs. They operate with flexible investment mandates and typically charge higher fees due to their active management style and use of advanced financial instruments. Their primary objective is to generate alpha, or market-beating returns, irrespective of overall market direction.
Who is an accredited investor, and what are AI-only funds and LVFs?
An accredited investor is a person certified by an accreditation agency, or by a specified SEBI-regulated entity, as meeting the income, net worth or securities market exposure tests in Regulation 2(1)(ab). Accreditation removes the ₹1 crore minimum ticket and opens two lighter-touch fund types: the Accredited Investors only fund (AI-only fund), and within it the large value fund (LVF), in which each investor commits at least ₹25 crore.
Table 6: Investor routes into an AIF from 15/10/2026
| Route | Who qualifies | Minimum commitment | What it opens |
|---|---|---|---|
| Regular investor | Any eligible resident or non-resident investor | ₹1 crore per scheme (₹25 lakh for employees or directors of the AIF or manager) | Regular Category I, II and III schemes |
| Accredited individual, HUF, family trust or sole proprietor | Income of ₹2 crore or more; or net worth of ₹7.5 crore or more with ₹3.75 crore in financial assets; or income of ₹1 crore or more with net worth of ₹5 crore or more (₹2.5 crore in financial assets); or securities market exposure of ₹5 crore or more | No regulatory minimum | AI-only funds, Angel Funds, co-investment schemes |
| Accredited LLP, body corporate or non-family trust | Net worth of ₹50 crore or more, or securities market exposure of ₹20 crore or more | No regulatory minimum | AI-only funds, Angel Funds, co-investment schemes |
| LVF investor | Accredited investor | ₹25 crore per investor | LVF schemes with 50% and 20% concentration limits and no standard PPM template |
| Person resident outside India | Deemed accredited under the proviso to Regulation 2(1)(ab) | No regulatory minimum outside LVFs | AI-only funds and LVFs, subject to FEMA |
The AI-only category came in through the SEBI (AIF) (Third Amendment) Regulations, 2025, notified on 18/11/2025, and SEBI’s circular dated 08/12/2025 allows existing schemes to convert with the approval of all investors. In an AI-only fund, the manager can carry out the trustee’s operational responsibilities. Choosing between a regular scheme, an AI-only fund and an LVF is a fund structuring decision that sets the investor base, the filing route and the investment limits together.
Co-investment schemes for accredited investors
From 08/09/2025, a Category I or II AIF can offer co-investment opportunities to its accredited investors through a separate co-investment scheme that invests in the unlisted securities of only one investee company (Regulation 2(1)(fb), inserted by the SEBI (AIF) (Second Amendment) Regulations, 2025). Only accredited investors of the main scheme can invest, and the co-investment cannot be on terms more favourable than those of the main scheme. The alternative route is a co-investment portfolio manager under the SEBI (Portfolio Managers) Regulations, 2020.
Key Investment Team of AIFs
The key investment team of the Investment Manager of all AIFs have to comply with certain qualification conditions which are specified below:
| Experience | Minimum 1 key person to obtain certification from the NISM by passing the NISM Series-XIX-C: Alternative Investment Fund Managers Certification Examination or NISM Series-XIX-D: AIF Cat I and II examination or NISM Series-XIX-E: AIF Cat III examination |
| Educational Qualification | Minimum 1 key person with professional qualification in any of the below from a university or an institution recognized by Central Government or any State Government or a foreign university: Finance Accountancy Business management Commerce Economics Capital markets or Banking CFA charter from the CFA institute |
Table 3: Criteria for Key Investment Team
The experience and education qualification criteria may be satisfied by the same person.
For Category I and II AIFs, the certification can be NISM Series-XIX-C or Series-XIX-D; for Category III AIFs, Series-XIX-C or Series-XIX-E. The June 2026 Master Circular also requires the compliance officer of the manager to hold NISM certification from 01/01/2027.
Taxation of Alternative Investment Funds (AIFs)
The taxation of Alternative Investment Funds (AIFs) in India depends on whether the fund enjoys pass-through status or is taxed at the fund level:
Category I and II AIFs: Pass-Through Status
Category I and II AIFs are granted pass-through status from an income-tax perspective, whereby any income earned by these AIFs (other than profits or gains from business) is not taxed at the AIF level, but directly taxed as income at the hands of the investors as if these investors had directly received this income from the investments.
Unabsorbed losses (other than business losses) of the AIF may be allocated to the investors for them to set off against their respective individual incomes, subject to such investors having held the units in the AIF for at least 12 months.
Further, the distributions from Category I and II AIFs are subject to a withholding tax of 10% in the case of resident investors, and at the rates in force in the case of non-resident investors (after giving due consideration to any benefit available to them under the applicable tax treaty).
The Finance Act, 2025 has introduced a clarificatory amendment to the definition of ‘capital asset’ by expressly including investments made by Category I and II AIFs. This amendment resolves the long-standing ambiguity regarding the characterization of income clarifying that gains from investments made by Category I and II AIF shall be taxable under the head ‘Capital Gains’.
- Income Taxed at Investor Level: Capital gains, dividends, and interest income are passed through and taxed in the investor’s hands.
- Exception: Business Income: Any income classified as “profits and gains from business or profession” is taxed at the AIF level (at corporate rates for companies/LLPs or the Maximum Marginal Rate (MMR) for trusts).
- Unabsorbed Losses: Business losses are retained by the AIF and can be carried forward at the fund level.
- Withholding Tax (TDS): AIFs typically deduct 10% TDS on passed-through income for resident investors, while in case of non-resident investors, it is as per DTAA.
From 01/04/2026, the pass-through regime continues under the Income-tax Act, 2025. Section 115UB of the Income-tax Act, 1961 corresponds to Section 224 of the 2025 Act, and TDS on distributions under Section 194LBB now falls under Section 393(1) for residents at 10% and Section 393(2) for non-residents. Investment funds report each unit holder’s share of income in Form 78 and file the consolidated annual statement in Form 79 under Rule 145 of the Income-tax Rules, 2026. The Finance Act, 2025 clarification that securities held by Category I and II AIFs are capital assets carries into the 2025 Act.
Table 7: Worked example, Category II AIF distribution to a resident individual (tax year 2026-27)
| Income passed through | Amount (₹) | Tax in the investor’s hands | TDS by the AIF at 10% (₹) |
|---|---|---|---|
| Long-term gain on unlisted shares held over 24 months | 20,00,000 | Capital gains at 12.5%: 2,50,000 | 2,00,000 |
| Short-term gain on listed shares, STT paid | 5,00,000 | Capital gains at 20%: 1,00,000 | 50,000 |
| Interest from portfolio debt | 3,00,000 | Slab rate, assumed 30%: 90,000 | 30,000 |
| Dividends | 2,00,000 | Slab rate, assumed 30%: 60,000 | 20,000 |
| Total | 30,00,000 | 5,00,000 before surcharge and 4% cess | 3,00,000, credited against the 5,00,000 |
The investor pays the balance of ₹2,00,000 (plus surcharge and cess) through advance tax or self-assessment. The AIF itself pays nothing on this income, because none of it is business income.
Category III AIFs: Non-Pass-Through Status
Category III AIFs have not been granted statutory pass-through status. Typically, they are set up as “determinate and irrevocable trusts.” This means the trusts have identifiable beneficiaries, and their respective beneficial interests can be determined at any given time. In such trusts, the trustee can discharge the tax obligation for the income of the trust on behalf of its beneficiaries (i.e., the investors) in a representative capacity. This is similar to the tax liability an investor would face if they had received the income directly. However, there’s an exception: trusts with any business income must pay tax at the MMR i.e., 39% where the trust pays tax under the new regime. As per income-tax law, tax authorities can recover tax either from the trustee or directly from the beneficiaries. Given this flexibility, a trustee might opt to pay the entire tax amount at the AIF level. Moreover, the law permits the trustee (acting as a representative assessee) to recover from investors any taxes it has paid on their behalf.
- Fund Pays Tax: All income (capital gains, interest, dividends, business income) earned by a Category III AIF is taxed at the fund level.
- Tax Rate: Often, particularly if structured as a trust, this income is taxed at the Maximum Marginal Rate (MMR) (depending on the nature of income).
- Distributions to Investor: Since tax is already paid at the fund level, distributions received by investors from Category III AIFs are generally tax-exempt in their hands. The tax can be collected from the trustee or, in certain circumstances, directly from the investor.
We have not covered tax implications for investment managers and sponsor entities above.
Key Documents
Private Placement Memorandum (PPM):
The PPM provides comprehensive details about the AIF. Contents include information about the manager, key investment team, targeted investors, proposed fees and expenses, scheme tenure, redemption conditions or limits, investment strategy, risk factors and management, conflict of interest procedures, disciplinary history, service terms and conditions by the manager, affiliations with intermediaries, winding up procedures, and any other relevant details helping investors make informed decisions about investing in an AIF scheme.
SEBI has introduced mandatory templates for PPMs, which provide for two parts:
- Part A: section for minimum disclosures
- Part B: supplementary section to allow full flexibility to the AIF in order to provide any additional information, which it may deem fit.
There are two templates: one for Category I and II AIFs and the other for Category III AIFs.
Angel Funds, LVFs and AIFs in which each investor commits to a minimum capital contribution of INR 70 crores are exempted from following the aforementioned template.
LVFs now need a minimum of ₹25 crore per investor (SEBI (AIF) (Third Amendment) Regulations, 2025), so the LVF exemption from the template now applies from that lower threshold.
Indenture of Trust / Trust Deed:
This document is an agreement between the settlor and the trustee. It involves the settlor transferring an initial settlement (can be nominal) to the trustee to create the fund’s assets. The Indenture details the roles and responsibilities of the trustee.
Investment Management Agreement:
This agreement is entered between the trustee and the investment manager. Here, the trustee designates the investment manager and transfers most of its management powers regarding the fund to them. However, certain powers retained by the trustee are outlined in the Indenture of Trust.
Contribution Agreement:
This agreement is between the contributor (investor), the trustee, and the investment manager. It mentions the terms of an investor’s participation in the fund, covering areas like beneficial interest computation, distribution mechanism, expense list to be borne by the fund, and the investment committee’s powers. SEBI mandates that the Contribution Agreement’s terms should align with the PPM and shouldn’t exceed its provisions.
Investment Process for AIFs (India)
- Check eligibility first. Investors must meet the minimum investment requirement of ₹1 crore and be prepared for a long-term commitment of 3-7 years, as AIFs are largely illiquid.
- Choose the right AIF category. Category I focuses on start-ups, venture capital, and infrastructure. Category II covers private equity, private credit, and real assets. Category III uses complex strategies, including leverage, suited for higher-risk appetites.
- Evaluate the fund manager. Review the manager’s track record, sector expertise, risk management approach, and alignment of interests. Historical performance helps with assessment but is not a guarantee of future returns.
- Complete KYC and banking setup. Investors must submit PAN, identity and address proofs. NRIs additionally require passport details and an operational NRE or NRO account with an Indian bank.
- Study the PPM carefully. The Private Placement Memorandum outlines strategy, fees, risks, governance standards, and exit timelines, making it a critical due-diligence document.
- Sign agreements and invest. Execute the contribution agreement and transfer capital to the designated AIF account as per the drawdown schedule.
Tenure and Listing of Alternative Investment Funds / Schemes
Understanding the tenure and liquidity aspects of AIFs is crucial for investors, as it dictates the duration of their capital commitment and the ease with which they can exit an investment.
Fund Tenure and Structure
The tenure of an Alternative Investment Fund, or its individual schemes, varies based on its category:
- Category I and Category II AIFs: These funds are typically structured as close-ended schemes. This means they have a predetermined lifespan.
- Minimum Tenure: The regulations stipulate a minimum tenure of three years from the date of final closing of the scheme.
- Extension: The tenure can be extended, generally by a maximum of two years, provided there is investor consent (usually requiring approval from a specified percentage, often two-thirds, of unit holders by value). This extension allows the fund manager more time to achieve investment objectives or liquidate assets optimally.
- Category III AIFs: Unlike Categories I and II, Category III AIFs offer more flexibility in their structure. They can be either open-ended or close-ended.
- Open-ended Category III AIFs allow investors to enter and exit at various points, subject to the fund’s terms and conditions (e.g., specific redemption windows, lock-in periods).
- Close-ended Category III AIFs operate similarly to Category I and II in terms of fixed tenure, often with a minimum of three years if structured as such. The choice between open-ended and close-ended depends on the fund’s investment strategy and the nature of its underlying assets.
Listing of AIF Units on Stock Exchanges
While AIFs are primarily private investment vehicles, SEBI regulations permit the optional listing of AIF units on recognized stock exchanges. This provision aims to offer a potential avenue for liquidity to investors.
- Optional Listing: Fund managers may choose to list the units of their AIF schemes on an exchange, but it is not mandatory. This decision is often influenced by investor demand and the fund’s strategy.
- Minimum Tradable Lot: For any listed AIF units, the minimum tradable lot is stipulated at ₹1 crore (Rupees One Crore). This ensures that trading remains restricted to sophisticated investors, aligning with the nature of AIFs.
- Reality of Limited Liquidity: Despite the option for listing, it’s crucial for investors to understand the reality of limited liquidity for AIF units on stock exchanges.
- Thin Trading Volumes: AIF units, even when listed, often experience thin trading volumes compared to mainstream equities or mutual funds. This is due to the nature of their underlying illiquid assets, the limited number of eligible sophisticated buyers and sellers, and the long-term investment horizon of many AIF investors.
- Investor Base: The investor base for AIFs primarily consists of HNIs and institutional investors, who typically have a longer investment horizon and are not engaged in frequent trading. This further contributes to lower trading activity.
- Impact on Exit: Consequently, while listing provides a theoretical exit route, actually selling units at a fair price and in a timely manner can be challenging. Investors should primarily view AIFs as long-term, illiquid investments and not rely on exchange listing for immediate or easy exit liquidity.
How does an AIF scheme wind up?
An AIF scheme winds up when its tenure, including any extension, ends, when 75% of investors by value resolve to wind it up, or when SEBI directs it. After tenure ends, the manager has a one-year liquidation period to sell the assets and distribute proceeds after meeting liabilities, and may distribute unliquidated investments in specie (Regulation 29, SEBI (AIF) Regulations, 2012).
Two 2026 changes matter for older funds. From 18/04/2026, distributions during winding up are subject to conditions SEBI specifies (Regulation 29(7)), and an AIF can be tagged an inoperative fund under new Regulation 29(10A). SEBI’s circular dated 16/06/2026 (HO/19/34/11(2)2026-AFD-POD1/I/13764/2026) sets out when a scheme may retain proceeds beyond its permitted life, for example for pending litigation or tax and regulatory proceedings, and gives inoperative funds lighter compliance until they surrender registration.
How to get registered with SEBI?
To register an AIF with SEBI, the fund needs to make an application to SEBI on its online portal.
The trust deed i.e. incorporation document of the fund where it is set up as a trust, needs to be registered with the local authorities. Further, the PAN needs to be obtained before making the application to SEBI.
The application to SEBI has the following key documents to be submitted:
- Application form in Form A
- Private Placement Memorandum (PPM)
- Trust Deed
- Declarations and KYC documents of the entities involved i.e. investment manager, sponsor, trustee (if the AIF is structured as a trust), and the AIF itself
Further, before submitting the application to SEBI, the AIF must engage a merchant banker who performs due diligence on the PPM and subsequently provides a certification that needs to be filed with SEBI. However, there’s an exemption for LVFs and Angel Funds for this requirement.
AI-only funds are also exempt from filing through a merchant banker (proviso to Regulation 12(3A), as amended on 14/07/2026).
Once the application is submitted, SEBI will evaluate the application. Generally, the entire AIF setup and registration process, including SEBI’s assessment, spans around four to six months. As of April 2026, SEBI has also introduced a Fast-Track Mechanism (Phase 1) permitting AIF schemes to begin soliciting investors 30 days after filing their PPM, without waiting for SEBI’s affirmative sign-off, subject to no objection being raised by the regulator.
That 30-day window has since been shortened. From 14/07/2026, a regular scheme can launch 10 working days after its PPM is filed (Regulation 12(2), as amended by the Second Amendment Regulations, 2026), while AI-only funds, LVFs and Angel Funds can launch on filing. The first scheme of a new AIF still waits for the certificate of registration, and pays no scheme fee.
Broadly, the process flow looks as follows:
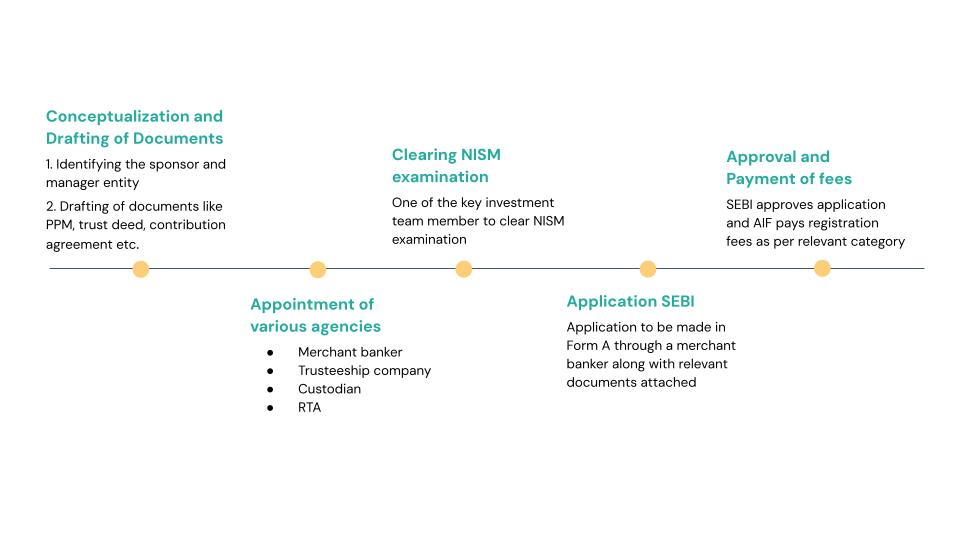
AIF Process Flow
Who Can Invest in an AIF?
- AIFs are open to resident Indians, NRIs and foreign nationals. The minimum investment is ₹1 crore per investor, or ₹25 lakh for employees and directors of the AIF or its manager.
- AIFs are “Not for Retail Investors” due to their inherent high risk, substantial costs, and lock-in period constraints.
- Each AIF scheme can have up to 1,000 investors. Angel Funds have no investor cap from 08/09/2025, when they moved to accredited investors only (SEBI (AIF) (Second Amendment) Regulations, 2025).
Alternative Investment Funds (AIFs) are designed for high-net-worth individuals (HNWI), institutional investors, and sophisticated investors. These investors typically include:
- High-net-worth individuals (HNWI)
- Corporate bodies
- Foreign investors (including NRIs and foreign nationals)
- Venture capital funds, private equity firms, and insurance companies
For a broader audience of investors looking to diversify their portfolios, it is important to understand that AIFs generally require a minimum investment of ₹1 crore (approximately $135,000), a barrier to entry for retail investors. Moreover, certain funds like Category III AIFs, which invest in more volatile assets like hedge funds, require highly experienced investors to take calculated risks.
How is an AIF different from a mutual fund and PMS?
An AIF pools money from a few sophisticated investors into mostly unlisted or complex strategies, with a ₹1 crore entry ticket and long lock-ins. A mutual fund pools retail money into mainly listed securities with daily liquidity. A portfolio management service (PMS) runs a separate portfolio in the investor’s own name, with a ₹50 lakh minimum.
Table 8: AIF vs mutual fund vs PMS
| Parameter | AIF | Mutual fund | PMS |
|---|---|---|---|
| Regulation | SEBI (AIF) Regulations, 2012 | SEBI (Mutual Funds) Regulations, 2026 | SEBI (Portfolio Managers) Regulations, 2020 |
| Minimum investment | ₹1 crore (accredited investors exempt) | No regulatory minimum | ₹50 lakh |
| Ownership | Units in a pooled vehicle | Units in a pooled vehicle | Securities held in the investor’s own demat account |
| Assets | Largely unlisted equity, private credit, real estate, complex strategies | Mainly listed securities | Mainly listed securities |
| Tax | Pass-through for Category I and II; fund-level for Category III | Taxed on redemption | Taxed as a direct holding |
| Liquidity | Category I and II close-ended | Daily for open-ended schemes | Exit any time, subject to exit load |
Factors to Consider Before Investing in AIFs
Investing in Alternative Investment Funds (AIFs) requires careful consideration due to their unique nature. Before investing, assess these critical factors:
- Risk Appetite and Tolerance: AIFs generally carry higher risk due to illiquid assets, early-stage investments, or complex strategies. Ensure your comfort with potential capital loss and volatility aligns with the AIF’s profile.
- Investment Horizon: AIFs typically involve long lock-in periods (often 3-7+ years). Confirm your financial goals allow for this extended capital commitment.
- Minimum Investment Requirement: Most AIFs mandate a minimum investment of ₹1 crore (or ₹25 lakh for Angel Funds). Ensure you meet this substantial entry barrier comfortably.
- Angel Funds no longer carry a ₹25 lakh minimum: from 08/09/2025 they accept only accredited investors, with no per-investor minimum. Accredited investors are also exempt from the ₹1 crore minimum in other schemes, except LVFs, which need ₹25 crore.
- Fund Manager’s Expertise: The fund’s success hinges on the manager’s experience, track record, and specialized knowledge. Thoroughly research their performance, strategy, and team.
- Liquidity Constraints: AIFs invest in illiquid assets. Even if listed, the ₹1 crore minimum tradable lot and thin trading volumes mean liquidity is severely limited. Do not rely on quick exits.
- Regulatory and Tax Implications: Understand the specific SEBI regulations and the tax treatment (pass-through for Cat I & II, non-pass-through/MMR for Cat III) to gauge post-tax returns and compliance.
Taxation of AIFs in India
Taxation plays a significant role in the decision-making process for potential investors in AIFs. Understanding the structure of taxation on both the fund and the investor level is crucial:
- Tax Structure for AIFs
- Category I & II AIFs are generally exempt from tax at the fund level. However, taxes are levied at the investor level when returns are distributed.
- Category III AIFs face higher tax rates due to the speculative nature of the investments. These funds are taxed at the fund level before returns are distributed.
- Taxation on Investors
- Investors in AIFs are subject to tax based on the type of income they receive.
- Income from AIFs may be classified as capital gains, dividends, or interest income, and the tax rate will depend on the holding period (short-term or long-term).
- Long-term capital gains (LTCG) from investments held for over three years are taxed at a reduced rate of 10% without indexation.
- This rate has changed. From 23/07/2024, long-term capital gains are taxed at 12.5% without indexation (Finance (No. 2) Act, 2024), and the long-term holding period is 12 months for listed securities and 24 months for unlisted shares and most other assets. From 01/04/2026, the rates sit in Sections 196 to 198 of the Income-tax Act, 2025.
Benefits of Investing in AIFs in India
AIFs offer several attractive benefits for high-net-worth individuals and institutional investors looking to diversify their portfolios. The key benefits include:
- High Return Potential With their focus on private equity, venture capital, and infrastructure, AIFs present higher growth potential than traditional investment vehicles like mutual funds.
- Diversification AIFs allow investors to diversify their portfolios beyond equity markets and debt instruments into alternative asset classes such as real estate, commodities, and startup investments.
- Professional Fund Management AIFs are managed by seasoned professionals who have a deep understanding of the market and provide strategic oversight of the investments, leading to better risk management and potentially higher returns.
- Lower Correlation with Stock Markets AIFs are often less correlated with equity market movements, providing a hedge against market volatility.
Final Thoughts
With their ability to diversify investment portfolios and provide potential high returns, AIFs undeniably present an attractive avenue for investment in today’s dynamic market scenario.The regulatory framework, set by SEBI, ensures transparency, credibility, and alignment with global best practices, further instilling confidence among stakeholders. However, AIFs can be tricky to understand because of the different types, how they are taxed, and the many documents involved. It’s like trying to put together a puzzle with lots of pieces.
India’s AIF industry continues its strong upward trajectory, driven by rising domestic capital, technology adoption, and regulatory maturity. As of March 2026, registered AIFs stood at 1,849, with cumulative commitments of Rs. 16.94 lakh crore and net investments of Rs. 6.76 lakh crore. By 30/09/2026, commitments had reached ₹18.68 lakh crore and investments ₹7.50 lakh crore. The accredited investor base has grown more than fivefold in a year to 3,820 investors, reflecting deepening participation from sophisticated capital. On the regulatory front, SEBI’s GARUDA mechanism, operational from 30/07/2026, signals a shift from upfront approval to a disclosure-led, risk-based model, cutting scheme launch timelines from 30 days to as few as 10 working days for regular schemes, and to immediate launch for Accredited Investor-only funds.
Fund managers are increasingly leveraging advanced analytics, AI-led risk monitoring, and automated compliance systems, with adoption expanding steadily through 2025. Private credit has solidified its position as a core strategy, contributing roughly 15% of total AIF commitments as of December 2024 (approximately Rs. 1.95 lakh crore), up from 6% five years prior, supported by tighter bank lending and demand for structured yield products. Domestic investors accounted for approximately 55% of funds raised in Category I and II AIFs as of September 2025, with HNIs, family offices, and institutions forming the dominant portion of that base; Total net AIF investments reached Rs. 5.38 lakh crore by March 2025, growing approximately 32% year-on-year from Rs. 4.07 lakh crore in March 2024. On the regulatory front, SEBI continues to strengthen disclosure, valuation, and governance norms while simplifying accreditation frameworks, reinforcing AIFs as a cornerstone of sophisticated portfolio construction in India.
For both potential AIF managers and investors, understanding this intricate ecosystem is crucial. It is recommended to talk to experts who know the details. They can guide you through the process, help you understand the rules, and make sure you’re making the best decisions. As the world of AIFs keeps changing, staying informed and getting the right advice will be key to success.
Need Expert Guidance in Setting up AIF?
At Treelife, we specialize in helping investors and fund managers navigate the complexities of the AIF landscape. Whether it’s AIF setup & registration with SEBI, fund structuring, or regulatory compliance, our team of experts is here to guide you through every step of the process.
Reach out to us today and ensure your AIF investment strategies are aligned with the latest regulations and market trends.
Contact Us: support@treelife.in
Call Us: +91 99301 56000
References:
- SEBI Website: https://www.sebi.gov.in/
- According to SEBI’s Data Relating to Activities of Alternative Investment Funds (AIFs).
- https://aifpms.com/blog/growth-of-aif-pms-investments-in-india/
- India Goes Alternatives report by Avendus, published in December 2024.
- CRISIL Intelligence and Oister Global report on AIFs, published in January 2025.
- CareEdge Advisory & Research, India Alternatives Industry Report, 2025; PwC India, Tapping Private Credit Opportunities, 2025.
- SEBI, Consultation on Green Channel AIF Rollout upon Document Acknowledgement (GARUDA Mechanism), May 2026: https://www.sebi.gov.in/reports-and-statistics/reports/may-2026/consultation-on-green-channel-aif-rollout-upon-document-acknowledgement-garuda-mechanism-for-processing-of-placement-memorandum-of-alternative-investment-funds-aifs-filed-with-sebi-_101340.html
FAQs on Alternative Investment Funds (AIFs) in India
Q: What is AIF in India?
A: In India, AIF stands for Alternative Investment Fund. It refers to any fund established or incorporated in India to pool capital from investors for investing in accordance with a defined investment policy. AIFs are typically used to invest in asset classes like private equity, venture capital, hedge funds, real estate, or other non-traditional investment avenues. The concept of AIFs was introduced by the Securities and Exchange Board of India (SEBI) in 2012, under the SEBI (Alternative Investment Funds) Regulations.
Q: What is the full form of AIF?
A: The full form of AIF is Alternative Investment Fund.
Q: How are AIFs regulated in India?
A: AIFs in India operate under the regulatory framework of the Securities and Exchange Board of India (SEBI). SEBI introduced the SEBI (Alternative Investment Funds) Regulations in 2012 to categorize AIFs as a distinct asset class. All entities desiring to function as an AIF must register with SEBI.
Q: What is the fund structure of an AIF?
A: The fund structure of an AIF can be a trust, company, LLP, or body corporate, though the trust structure is most common in India. The structure governs how the fund is managed and defines the roles of key stakeholders. A typical AIF structure consists of several key entities:
- Sponsor: Sets up the AIF.
- Trustee: Holds the fund’s assets for the benefit of investors.
- Investment Manager: Manages the fund’s portfolio and makes investment decisions.
- Contributor (Investor): The individuals or institutions providing capital.
- Custodian: Responsible for the safekeeping of the fund’s assets and securities.
- Other key parties: The structure also involves a Merchant Banker for regulatory filings and a Registrar and Transfer Agent (RTA) to maintain investor records.
Q: What are the different categories or types of AIFs?
A: SEBI classifies AIFs into three categories or types:
- Category I AIF: Focus on sectors or areas which are socially or economically desirable. Includes Venture Capital Funds, SME funds, and more.
- Category II AIF: Funds that do not fall under Category I or III and don’t undertake excessive leverage.
- Category III AIF: Funds employing diverse or complex trading strategies, often using leverage. Examples include hedge funds.
Q: How does the AIF fee structure work?
A: The AIF fee structure consists of compensation for the Investment Manager, which is primarily made up of a management fee and a performance fee.
- Management Fee: A recurring fee paid to the Investment Manager for managing the fund.
- Performance Fee (Carry or Carried Interest): This is a share of the fund’s profits that is paid to the Investment Manager. This fee is typically in the range of 15% to 20% of the profits earned after the investors’ returns have crossed a minimum threshold known as the “Hurdle Rate”.
Q: How is the taxability of AIFs determined?
A: Taxability depends on the category of the AIF:
- Category I and II AIFs: Granted pass-through status, meaning income (other than business profits) is taxed directly in the hands of investors.
- Category III AIFs: Not granted a statutory pass-through. Typically, tax liability for trusts can be met by the trustee or the beneficiaries directly.
Q: What charges are associated with AIFs?
A: In addition to the core fee structure, there are several other charges associated with AIFs. These must be fully disclosed in the fund’s Private Placement Memorandum (PPM). The key charges include:
- Regulatory Fees: This includes a one-time SEBI registration fee and a per-scheme filing fee, with costs varying by the AIF’s category.
- Set-up & Administrative Charges: These are general operational expenses covering the fund’s set-up, legal services, auditing, compliance, and reporting.
- Third-Party Service Charges: Fees paid for essential services provided by the Custodian, Merchant Banker, and Registrar and Transfer Agent (RTA).
Q: What are Angel Funds and how do they fit into the AIF landscape?
A: Angel Funds are a sub-category of Category I AIFs, specifically Venture Capital Funds. They are designed to support the crucial role of angel investors in the startup ecosystem. From 08/09/2025, Angel Funds raise money only from accredited investors and invest between ₹10 lakh and ₹25 crore in each investee company.
Q: How does one register an AIF with SEBI?
A: To register with SEBI, the fund must make an online application. Prior to this, the trust deed must be registered locally, and a PAN should be obtained. Key documents like the PPM, Trust Deed, and relevant KYC documents must be submitted. The entire setup and registration process usually takes around four to six months. Once the AIF is registered, a regular scheme can launch 10 working days after its PPM is filed with SEBI (Regulation 12(2), as amended from 14/07/2026).
Q: Can AIF raise money from foreign investors?
A: Yes, an AIF is allowed to raise funds from a person resident outside India. However, AIF has to file Form InVi for issuing units to residents outside India.
Q: Can an AIF invest in overseas securities?
A: AIFs are permitted to invest in overseas securities, subject to obtaining of approval from SEBI by submitting an application. These investments are also subject to an industry-wide overall limit of USD 1,500 million. Such investments shall not exceed 25% of the investable funds of the scheme of the AIF. Further, the AIF is allowed to invest 25% of its investible funds in overseas securities. The USD 1,500 million industry-wide limit continues under the SEBI Master Circular for AIFs dated 03/06/2026.
Q: What are the asset class in which an AIF can invest?
A: AIFs are permitted to invest exclusively in financial instruments such as equity shares, share warrants, preference shares, debentures, and security receipts issued by securitization trusts. However, they are prohibited from making direct investments in tangible assets.
Q: Can returns be linked to individual investments for AIF investors?
A: Generally, returns in an AIF are calculated based on the overall performance of the fund’s portfolio rather than on a deal-by-deal basis.
Q: Can sponsor and Investment manager be the same person?
A: Yes, it is possible for the same entity to act as sponsor and investment manager both.
Q: What is the validity of registration of AIF?
A: The certificate of registration of an AIF shall be valid till the AIF is wound up.
Q: Can an AIF change its category after registration?
A: Yes. As per Circular No. CIR/IMD/DF/12/2013 dated 7th August 2013, an AIF can apply for a category change only if it hasn’t made any investments in the original category. The application must be submitted in Form A with supporting documents and an application fee of INR 1,00,000/- to SEBI. No registration fees are required for such applications. The change is allowed only if no commitments have been received, or if commitments exist, an option to withdraw them must be provided. The 2013 circular now stands rescinded, with its content consolidated into the SEBI Master Circular for AIFs dated 03/06/2026.
Q: Is it mandatory for an AIF to appoint a custodian?
A: As per SEBI circular no. SEBI/HO/AFD/PoD/CIR/2024/5 dated 12 January 2024, it is mandatory for a newly launched AIF to appoint a custodian irrespective of the Fund size. The requirement now sits in the SEBI Master Circular for AIFs dated 03/06/2026 and covers existing schemes too: schemes already holding an investment on 12/01/2024 had to appoint a custodian by 31/01/2025.
Q: Is it mandatory for an AIF to issue units in demat form?
A: As per SEBI circular no. SEBI/HO/AFD/PoD1/CIR/2023/186 dated 11 December 2023, it is mandatory for a newly launched AIF to issue units in dematerialised form to the investors irrespective of the Fund size. This requirement is now consolidated in the SEBI Master Circular for AIFs dated 03/06/2026.
Q: Who can invest in AIF?
A: Alternative Investment Funds (AIFs) can be invested in by Indian residents, Non-Resident Indians (NRIs), foreign nationals, and institutional investors, subject to regulatory requirements. AIFs are intended for high-net-worth and sophisticated investors due to the high minimum investment threshold.
Q: How AIFs differ from Mutual Funds?
A: The key differences are:
- Investment Scope: AIFs invest in alternative and unlisted assets; mutual funds invest mainly in listed securities.
- Investor Type: AIFs are for high-net-worth investors; mutual funds are suitable for retail investors.
- Minimum Investment: AIFs have high entry thresholds; mutual funds allow small investments.
- Risk & Returns: AIFs carry higher risk with potential for higher returns; mutual funds are relatively lower risk.
- Liquidity: AIFs have limited liquidity and lock-ins; mutual funds offer easier entry and exit.
Q: What are the SEBI AIF regulations?
A: The SEBI (Alternative Investment Funds) Regulations, 2012 are the rules under which every AIF in India registers, raises money, invests and winds up. They were last amended by the SEBI (AIF) (Third Amendment) Regulations, 2026, in force from 15/10/2026, and the SEBI Master Circular for AIFs dated 03/06/2026 sets out the operating detail.
Q: What is the GARUDA mechanism for AIFs?
A: GARUDA (Green-Channel: AIF Rollout Upon Document Acknowledgement) is SEBI’s fast-launch route for AIF schemes, in force from 14/07/2026. A regular scheme can launch 10 working days after filing its PPM through a merchant banker, while AI-only funds, LVFs and Angel Funds can launch on filing (SEBI circular HO/19/19/11(2)2026-AFD-RAC2/I/17617/2026 dated 30/07/2026).
Q: What is the minimum investment in an AIF in 2026?
A: The minimum is ₹1 crore per investor per scheme, or ₹25 lakh for employees or directors of the AIF or its manager (Regulation 10, SEBI (AIF) Regulations, 2012). Accredited investors have no minimum except in LVFs, where each investor commits at least ₹25 crore. Individuals can invest ₹1,000 or more in social impact funds from 18/04/2026.
Q: What is an Accredited Investors only fund?
A: An AI-only fund is an AIF or scheme in which every investor, other than the manager, sponsor and their employees or directors, is an accredited investor. The category was created by the SEBI (AIF) (Third Amendment) Regulations, 2025 from 18/11/2025, and such funds file their PPM without a merchant banker and can launch on filing.
Q: Has the SEBI Master Circular for AIFs been updated in 2026?
A: Yes. SEBI issued a new Master Circular for AIFs on 03/06/2026 (HO/19/34/11(6)2025-AFD-POD1/I/12928/2026), replacing the Master Circular dated 07/05/2024. It has since been updated for the winding-up circular of 16/06/2026, the GARUDA circular of 30/07/2026 and the angel fund timeline circular of 07/09/2026.